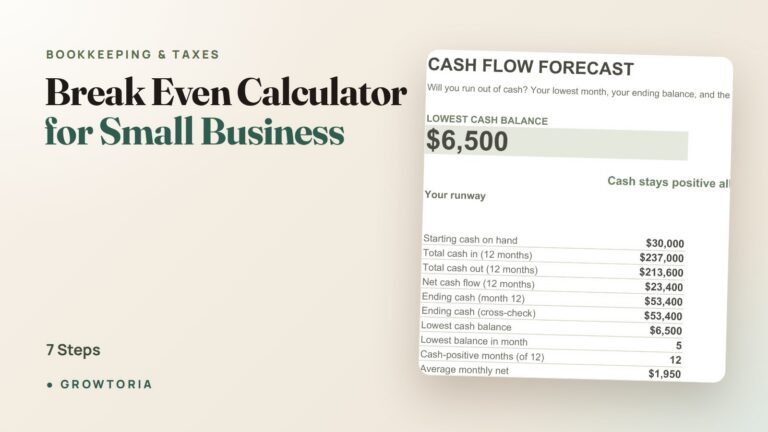
ANZ Small Business Cash Flow Forecast Template (2026)
An ANZ small business cash flow forecast template has to do something a generic US-style template never does: plan for the cash that passes through your account but belongs to the ATO or Inland Revenue. GST, PAYG withholding, superannuation, KiwiSaver and provisional tax all go out on fixed dates. If your forecast doesn’t show those dates, a profitable quarter can still leave you short on the 28th.
This guide is for owners in Australia and New Zealand: tradies, cafés, online sellers, consultants and agencies. It covers the lines to add, the dates to plan around, and a worked example you can copy into your own sheet.
Quick answer: An ANZ small business cash flow forecast template is a 12-month spreadsheet that lists expected cash in and out by month, with separate lines for GST, BAS or GST returns, PAYG or PAYE, super or KiwiSaver, and provisional tax. Put each one in the month it’s actually paid, not the month you earn it, so tax-heavy months don’t catch you out.
What makes an ANZ small business cash flow forecast template different?
The difference is timing. Australian and New Zealand businesses collect tax for the government all year, then pay it in lumps on set dates. A generic template treats every dollar in the bank as yours. A forecast built for ANZ separates the tax money first.
Our general small business cash flow template setup guide covers the basic structure: opening balance, cash in, cash out, closing balance. This article adds what Australian and New Zealand owners need on top of that.
Australia vs New Zealand: the lines that change
Here’s how the tax side of the forecast differs between the two countries. Use it to check that your sheet has every row it needs.
| Forecast item | Australia | New Zealand |
|---|---|---|
| Financial year | 1 July – 30 June | 1 April – 31 March (standard balance date) |
| GST rate | 10% (1/11 of a GST-inclusive price) | 15% (3/23 of a GST-inclusive price) |
| GST registration threshold | $75,000 annual turnover | $60,000 over 12 months |
| How GST is paid | Through the BAS, usually quarterly | GST return, filed monthly, two-monthly or six-monthly |
| Typical payment dates | Quarterly BAS: 28 Oct, 28 Feb, 28 Apr, 28 Jul | Set by your filing period (often the 28th of the month after it ends) |
| Employee tax | PAYG withholding (on the BAS) | PAYE (filed and paid each payday) |
| Retirement contributions | Super guarantee at 12% of ordinary time earnings | Employer KiwiSaver minimum (3.5% from 1 April 2026) |
| Income tax in advance | PAYG instalments (on the BAS or IAS) | Provisional tax, standard dates 28 Aug, 15 Jan, 7 May |
Rates and dates change, so check your own obligations with the ATO, or with Inland Revenue’s GST guidance if you’re in New Zealand. Your registered tax agent may also have lodgement dates later than the standard ones above.
Which rows should your cash flow forecast include?
Your forecast needs three blocks: cash in, operating cash out, and a separate tax and compliance block. Keeping tax on its own makes the dangerous months obvious at a glance.
Cash in
- Sales received (GST-inclusive): enter cash when it actually lands, not when you send the invoice.
- Debtor collections: if your terms are 30 days, December’s invoices are January’s cash.
- Other income: grants, interest, asset sales, owner top-ups.
- GST refunds: if you buy more than you sell in a period (common in a fit-out or launch quarter).
Operating cash out
- Stock and materials (GST-inclusive)
- Rent, utilities, insurance, software
- Net wages (what actually lands in employees’ accounts)
- Loan repayments and equipment finance
- Owner drawings
If you’re not sure how to group these, our list of bookkeeping categories for small business maps well to forecast rows.
Tax and compliance block
- GST payable: GST collected minus GST credits, placed in the month the BAS or GST return is due.
- PAYG withholding / PAYE: the tax held back from wages.
- Super or KiwiSaver: employer contributions, plus employee KiwiSaver deductions in NZ.
- PAYG instalments / provisional tax: income tax paid in advance.
- Annual items: workers’ compensation (AU) or ACC levies (NZ), insurance renewals, accountant fees.
How do you forecast GST and BAS payments month by month?
Work out the net GST each month, then add it up and drop the total into the month it’s due. In Australia, divide GST-inclusive sales by 11 to get GST collected. In New Zealand, multiply by 3/23.
- Estimate GST-inclusive sales for each month.
- Calculate GST collected: sales ÷ 11 (AU) or sales × 3/23 (NZ).
- Calculate GST credits on purchases the same way. Leave out wages, super and GST-free items.
- Subtract credits from collected to get net GST for the month.
- Add up the months in each period and put the total in the due month as a cash-out line.
If you’re on the cash basis, use the dates money changed hands. If you’re on the accruals basis, use invoice dates for GST but keep the forecast’s sales line on cash dates. That gap is exactly why accruals businesses get squeezed.
Worked example: a Brisbane café’s October
Take a café taking $40,000 a month (GST-inclusive) and spending $18,000 a month on GST-taxable supplies. It lodges quarterly BAS and withholds $2,400 PAYG a month from wages.
- GST collected per month: $40,000 ÷ 11 = $3,636
- GST credits per month: $18,000 ÷ 11 = $1,636
- Net GST per month: $2,000, so $6,000 for July to September
- PAYG withheld for the quarter: $7,200
- BAS payment due 28 October: $13,200
Normal months might leave the café $4,000 to $6,000 ahead. October then shows a $13,200 bill on top of normal costs. If the forecast spreads that across three months as “tax expense”, the owner never sees the hole coming. If it puts the bill in October, they can see it from July and set the money aside.
How should super, PAYE and provisional tax appear?
Put each one in the month it leaves your account. The common mistake is entering gross wages as one line, which hides the payments that go to the ATO, IRD or a super fund on a different date.
Australia: super and Payday Super
The super guarantee rate is 12% of ordinary time earnings. Super used to be paid quarterly. Under Payday Super, which starts 1 July 2026, employers have to pay super at the same time as wages, within about seven days of payday. That turns a quarterly lump into a smaller cost every pay cycle.
For your forecast, that means:
- Delete any quarterly super lump from July 2026 onwards.
- Add super as a line every pay cycle, next to net wages.
- Expect the first quarter to feel tighter if you’re still paying the last quarterly amount while the new per-pay payments start.
New Zealand: PAYE, KiwiSaver and provisional tax
PAYE and KiwiSaver deductions are filed each payday, so they sit in the same months as wages. Provisional tax is the one that catches people out. On the standard option with a 31 March balance date, the instalments are due 28 August, 15 January and 7 May.
The January payment lands just after the Christmas shutdown, when many trade and service businesses have their weakest cash month. Forecast it from at least October.
How do you build the forecast in under an hour?
Start from last year’s real bank data, not guesses. Most owners can rough out 12 months in one sitting if their bookkeeping is up to date.
- Export 12 months of bank transactions from your accounting software or bank.
- Set your forecast to start on your financial year: July for Australia, April for New Zealand. Tax dates line up more cleanly that way.
- Enter your opening bank balance for month one.
- Fill in fixed costs first: rent, loans, software, insurance.
- Add sales by month using last year’s pattern, adjusted for known changes such as a new contract or a price rise.
- Calculate the tax block using the GST steps above and put each payment on its due date.
- Set a minimum cash buffer and highlight any month where the closing balance falls below it.
- Update monthly: replace each forecast month with actual figures as it closes, and roll the plan forward a month.
Step 8 is what keeps the forecast useful. If you already do a weekly bookkeeping routine like our 30-minutes-a-week DIY bookkeeping method, add the monthly update to the last session of each month.
The government’s business.gov.au cash flow guidance is also worth reading for ways to improve cash flow once your forecast shows where it’s short.
The done-for-you shortcut
If you’d rather not build the formulas yourself, our 12-Month Cash Flow Forecast Spreadsheet gives you the full structure ready to fill in. It works in Google Sheets and Excel, so you can share it with your bookkeeper or accountant.
It’s a solid base for an ANZ small business cash flow forecast template because you can:
- Rename the expense rows to GST payable, PAYG withholding, super or KiwiSaver, and provisional tax.
- Start month one in July or April to match your financial year.
- See your monthly closing balance and runway calculated automatically.
- Enter real figures each month and see how far they drift from the plan.
It’s a digital download, so you can start this afternoon. If you prefer buying through Etsy, you can also grab it on our Etsy shop.
Before you fill it in, run your numbers through the free break-even calculator for small business. Knowing your monthly break-even sales figure makes the cash-in rows much easier to sanity-check.
What are the warning signs your forecast is showing?
A forecast is only useful if you act on it. Watch for these patterns:
- A dip below your buffer in a BAS or provisional tax month. Start setting aside a fixed share of each deposit now. Many owners move 10–15% of every sale into a separate tax account.
- Closing balance falling for three months in a row, even in non-tax months. That’s a margin or pricing problem, not just a timing problem.
- Debtor collections well behind sales. Tighten your payment terms or chase invoices sooner.
- Growth months that drain cash. More stock and staff go out before the extra sales come in.
If any of these keep coming up, our breakdown of cash flow issues for small businesses and how to fix them goes through the causes one at a time.
Frequently asked questions
Does ANZ bank provide a cash flow forecast template?
Several Australian and New Zealand banks, ANZ included, publish free business planning resources, and what’s on offer changes over time, so check your bank’s business hub. Whichever template you use, make sure it has separate lines for GST, BAS or GST returns, super or KiwiSaver, and provisional tax. Many basic bank templates don’t.
Should my forecast include GST in sales figures?
Yes. A cash flow forecast tracks actual money, and your customers pay you GST-inclusive amounts. Enter sales and purchases including GST, then show the net GST payment as a separate cash-out line in the month it’s due.
How far ahead should a small business forecast cash flow?
Twelve months is the standard for planning and for bank or lender conversations. If cash is tight, also keep a 13-week weekly view so you can see individual paydays and BAS dates. Update both at least once a month.
Is a cash flow forecast the same as a budget?
No. A budget or profit and loss shows whether you make money over a period. A cash flow forecast shows when money actually moves in and out of the bank. A business can be profitable on paper and still run out of cash because of payment timing and tax dates.
Can I use one template for both Australia and New Zealand?
Yes, if you can change the rows and the start month. Swap the GST formula (1/11 for Australia, 3/23 for New Zealand), start the year in July or April, and rename the payroll tax lines. Businesses that trade in both countries should keep a separate tab for each entity.